Agricultural Lending Responsibilities
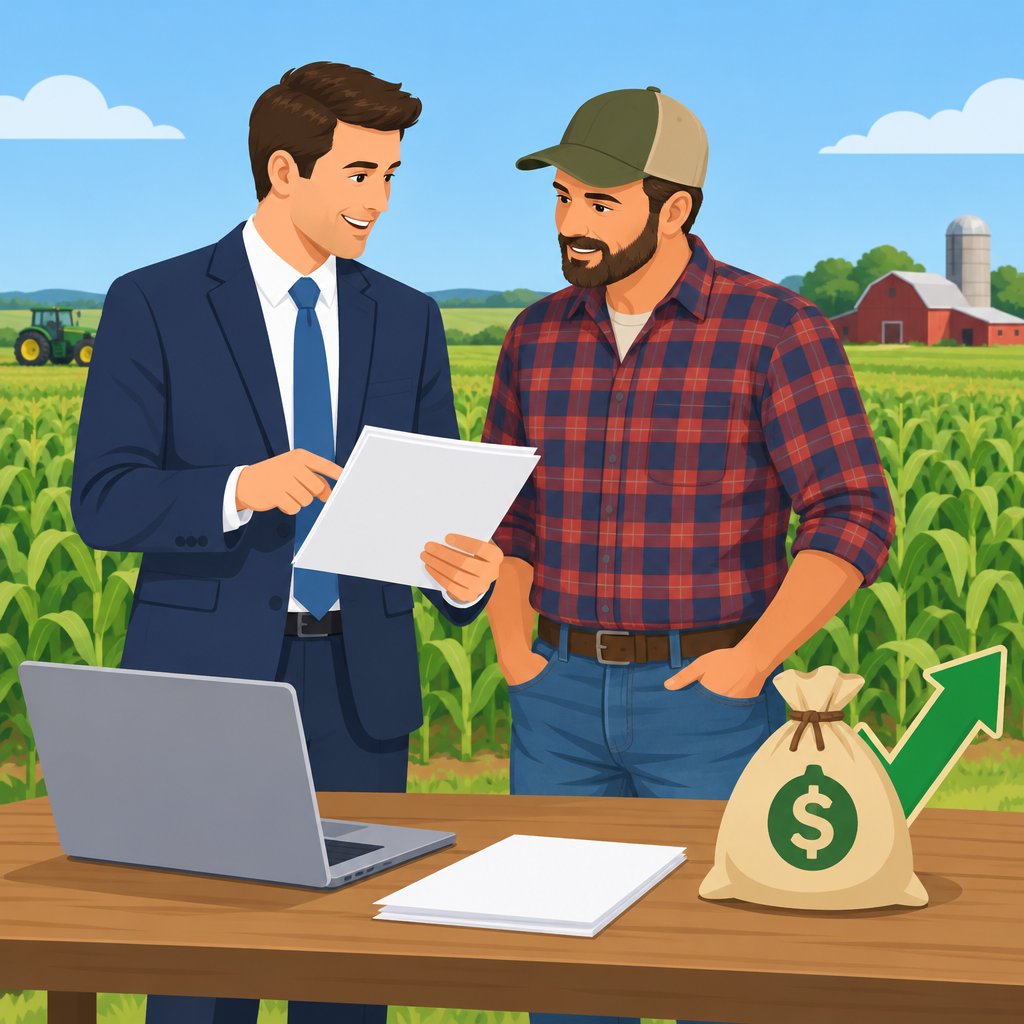
Agricultural loan officers assess loan applications from farmers.
They evaluate creditworthiness and review financial statements.
Additionally, they recommend loan approvals or rejections.
Importance of Lending Regulations
Key regulations guide agricultural loan officers throughout the lending process.
These requirements protect lender interests and encourage responsible lending practices.
They also support consistent and accountable loan decisions.
Regulatory Compliance Requirements
Agricultural loan officers must follow applicable federal and state regulations.
Important requirements include the Truth in Lending Act (TILA).
They must also comply with the Fair Credit Reporting Act (FCRA).
Risk Management in Agricultural Lending
Regulatory compliance helps officers identify risks associated with agricultural lending.
For example, farmers may face crop failures or market fluctuations.
Therefore, officers can manage lending risks more responsibly.
Protecting Agricultural Borrowers
Compliance helps ensure that farmers receive fair treatment.
It also helps prevent predatory lending practices.
As a result, borrowers receive stronger protection during the lending process.
Ethical Lending Standards
Following regulations supports ethical conduct among agricultural loan officers.
Moreover, compliance promotes trust between officers and farmers.
It also strengthens relationships with lending institutions.
Professional Development and Regulatory Knowledge
Officers who stay informed can strengthen their professional skills.
They also expand their knowledge of agricultural lending requirements.
Consequently, they serve clients better and protect their institutions.
Responsible Agricultural Lending Practices
Regulatory knowledge helps officers manage lending risks effectively.
It protects farmers and supports ethical lending decisions.
Ultimately, compliance strengthens responsible agricultural lending practices.
Licensing and Registration Requirements
- Agricultural loan officers need licenses and registrations to perform their duties legally and effectively.
- Requirements vary by location and may change during a loan officer’s career.
- Employers often expect specific qualifications or certifications for this role.
These requirements help ensure that loan officers possess appropriate knowledge and competence.
Agricultural loan officers typically need a license or registration in each state where they practice.
Applicants may submit education and experience records, complete applications, and pay required fees.
Because requirements differ, professionals should review the regulations in their practice area.
Employers may also require education or experience in finance or agriculture.
Some lenders require candidates to pass certification exams demonstrating relevant knowledge and expertise.
These qualifications help officers address the challenges and complexities of agricultural lending.
By meeting applicable requirements, professionals can pursue this career with greater confidence.
Compliance with Federal Laws
Agricultural loan officers must follow key federal laws.
These laws affect lending procedures and protect borrowers.
Furthermore, non-compliance can create penalties, fines, and financial risks.
- Agricultural loan officers must follow key federal laws.
- These laws affect lending procedures and borrower protections.
- Non-compliance can result in penalties or fines.
A thorough understanding of these laws supports compliant agricultural lending practices.
Failure to comply can create legal risks for lending institutions and borrowers.
Therefore, officers should apply these requirements throughout the lending process.
Key Federal Laws for Agricultural Loan Officers
Several federal laws establish important requirements for agricultural loan officers.
These requirements promote fair treatment, transparent terms, and responsible information handling.
Transform Your Career Today
Unlock a personalized career strategy that drives real results. Get tailored advice and a roadmap designed just for you.
Start NowOfficers should understand each law before processing agricultural loan applications.
- The Equal Credit Opportunity Act prohibits discrimination based on protected borrower characteristics.
- The Truth in Lending Act requires disclosures about loan terms and costs.
- The Fair Credit Reporting Act regulates consumer credit information collection, use, and distribution.
- The Agricultural Credit Act provides guidelines for lending to farmers and agricultural businesses.
Effects on the Lending Process
Following federal laws supports fair and transparent lending practices.
Moreover, compliance reduces legal disputes and strengthens borrower trust.
Borrowers receive protection from discrimination, predatory tactics, and unfair treatment.
Consequently, lending institutions can build stronger relationships with agricultural communities.
These relationships can support sustainable partnerships and mutual growth.
Consequences of Non-Compliance
Failure to follow federal laws can produce serious consequences for agricultural loan officers.
Regulators or borrowers may pursue legal actions against the lending institution.
The institution may also face financial penalties, legal fees, and reputational damage.
For example, discriminatory lending under ECOA can result in fines and lost business opportunities.
Likewise, TILA or FCRA violations can trigger sanctions, lawsuits, and negative publicity.
These outcomes can weaken institutional finances and undermine borrower confidence.
Accordingly, officers should prioritize compliance, ethical standards, and financial inclusivity.
Find Out More: Exploring Sustainable Fisheries and Aquaculture
Understanding State Regulations
- State regulations for agricultural lending vary by location and can affect loan approval.
- It is crucial for agricultural loan officers to understand the laws governing their state.
- Therefore, officers must remain informed and compliant to avoid legal issues.
Variation in State Regulations
State regulations can differ significantly from one state to another.
Each state establishes laws governing agricultural loan processing, approval, and management.
These rules may affect eligibility criteria, interest rates, and repayment terms.
Importance of Staying Informed
Staying informed helps agricultural loan officers avoid legal repercussions.
Additionally, compliance supports accurate information and better service for borrowers.
Failure to follow state laws can result in fines, legal action, or license loss.
Resources for Agricultural Loan Officers
State government websites can help officers monitor regulatory changes.
Industry publications and training programs also provide compliance information.
Moreover, conferences, workshops, seminars, and legal counsel can strengthen regulatory knowledge.
Learn More: How to Publish Research in Plant Pathology
Ethics and Professional Conduct
Agricultural loan officers must follow ethical guidelines and professional conduct standards.
These standards help them maintain trust and integrity throughout the lending process.
Therefore, officers should communicate honestly, protect information, and follow applicable requirements.
- Officers should prioritize honesty and transparency when interacting with clients.
- They must respect client confidentiality at all times.
- Officers should avoid conflicts of interest and promptly disclose potential conflicts.
- They must follow relevant laws and regulations governing the lending industry.
- Officers should provide accurate information and act in their clients’ best interests.
Ethical Behavior and Client Relationships
Ethical behavior plays an important role in building strong client and community relationships.
Furthermore, ethical conduct supports trust and credibility in long-term partnerships.
It also demonstrates professionalism and supports social responsibility within the community.
- Ethical conduct fosters trust and credibility with clients.
- By acting ethically, officers can strengthen their professional reputation.
- Strong ethical standards can help officers attract more clients.
- Ethical behavior demonstrates a commitment to professional standards.
- It helps create a positive impact and promote social responsibility.
Managing Ethical Dilemmas
However, agricultural loan officers may encounter ethical dilemmas during their work.
They must address these situations carefully while preserving integrity and professional standards.
Consequently, officers should balance client responsibilities with their duty to provide accurate information.
- A client may provide misleading information about their financial status.
- Officers must balance client duties with reporting obligations to the lending institution.
- Superiors may pressure officers to approve loans that fail necessary criteria.
- Officers must navigate these situations while upholding ethical standards.
See Related Content: The Art of Grape Selection for Winemaking
Consumer Protection Laws
Consumer protection laws govern agricultural lending and help protect borrowers.
These rules require fair treatment throughout the lending process.
Moreover, compliance helps prevent discrimination and predatory lending.
- Understand the laws that govern agricultural lending to protect consumers.
- Compliance with consumer protection laws ensures fair treatment of borrowers.
- Transparency in lending practices builds trust and fosters long-term relationships.
- Loan officers must follow regulations to prevent discrimination or predatory lending.
Importance of Transparency and Fairness
Transparency gives borrowers clear information about loan terms and conditions.
Fair practices also support equal access to credit for qualified individuals.
Consequently, ethical lending can strengthen trust between borrowers and lenders.
Transform Your Career Today
Unlock a personalized career strategy that drives real results. Get tailored advice and a roadmap designed just for you.
Start Now- Transparent lending practices build credibility and trust with borrowers.
- Fairness in lending ensures equal access to credit for all qualified individuals.
- Compliance with laws promotes ethical behavior and responsible lending practices.
- Consumer protection laws protect borrowers from deceptive or unfair practices.
Tips for Ensuring Compliance
Loan officers can support compliance by staying informed about current requirements.
Clear communication and thorough records make lending activities easier to review.
Regular policy reviews and staff training help maintain compliant lending practices.
- Stay informed about current consumer protection laws and regulations.
- Provide clear and accurate information about loan terms and conditions.
- Document all communications and transactions to support transparency.
- Regularly review and update lending policies and procedures.
- Train staff on compliance requirements and ethical lending practices.
- Seek legal advice when compliance issues create uncertainty.
Delve into the Subject: Career Growth Opportunities for Animal Nutritionists
Risk Management and Loan Underwriting
- Understanding risk management helps loan officers address potential challenges in agricultural lending.
- Risk management identifies, assesses, and reduces risks that could affect loan outcomes.
- Meanwhile, loan underwriting evaluates a borrower’s creditworthiness and ability to repay.
Importance of Risk Management
- Effective risk management helps loan officers make informed decisions and reduce potential defaults.
- By identifying risks early, officers can implement strategies that minimize their effects on loan performance.
- Furthermore, proper risk management protects institutional financial health and supports long-term sustainability.
Thorough Loan Underwriting
- Thorough underwriting helps officers assess repayment capacity and financial obligations.
- It requires gathering and analyzing financial information, reviewing credit history, and evaluating financial stability.
- Consequently, comprehensive underwriting clarifies the risks associated with each borrower.
Strategies for Mitigating Risks
- Loan portfolio diversification can reduce exposure to sector-specific agricultural risks.
- By distributing loans across sectors, officers can limit the effect of risks affecting one sector.
- Additionally, clear loan terms should define repayment schedules and collateral requirements.
- Regular monitoring supports timely intervention when loans show signs of increased risk.
Regulatory Compliance in Agricultural Lending
Agricultural loan officers must follow key regulations.
The Truth in Lending Act is one such regulation.
Regulatory compliance supports the integrity and success of agricultural lending operations.
Additional Resources
Google search results for Key Regulations for Agricultural Loan Officers Agricultural
Bing search results for Key Regulations for Agricultural Loan Officers Agricultural


